


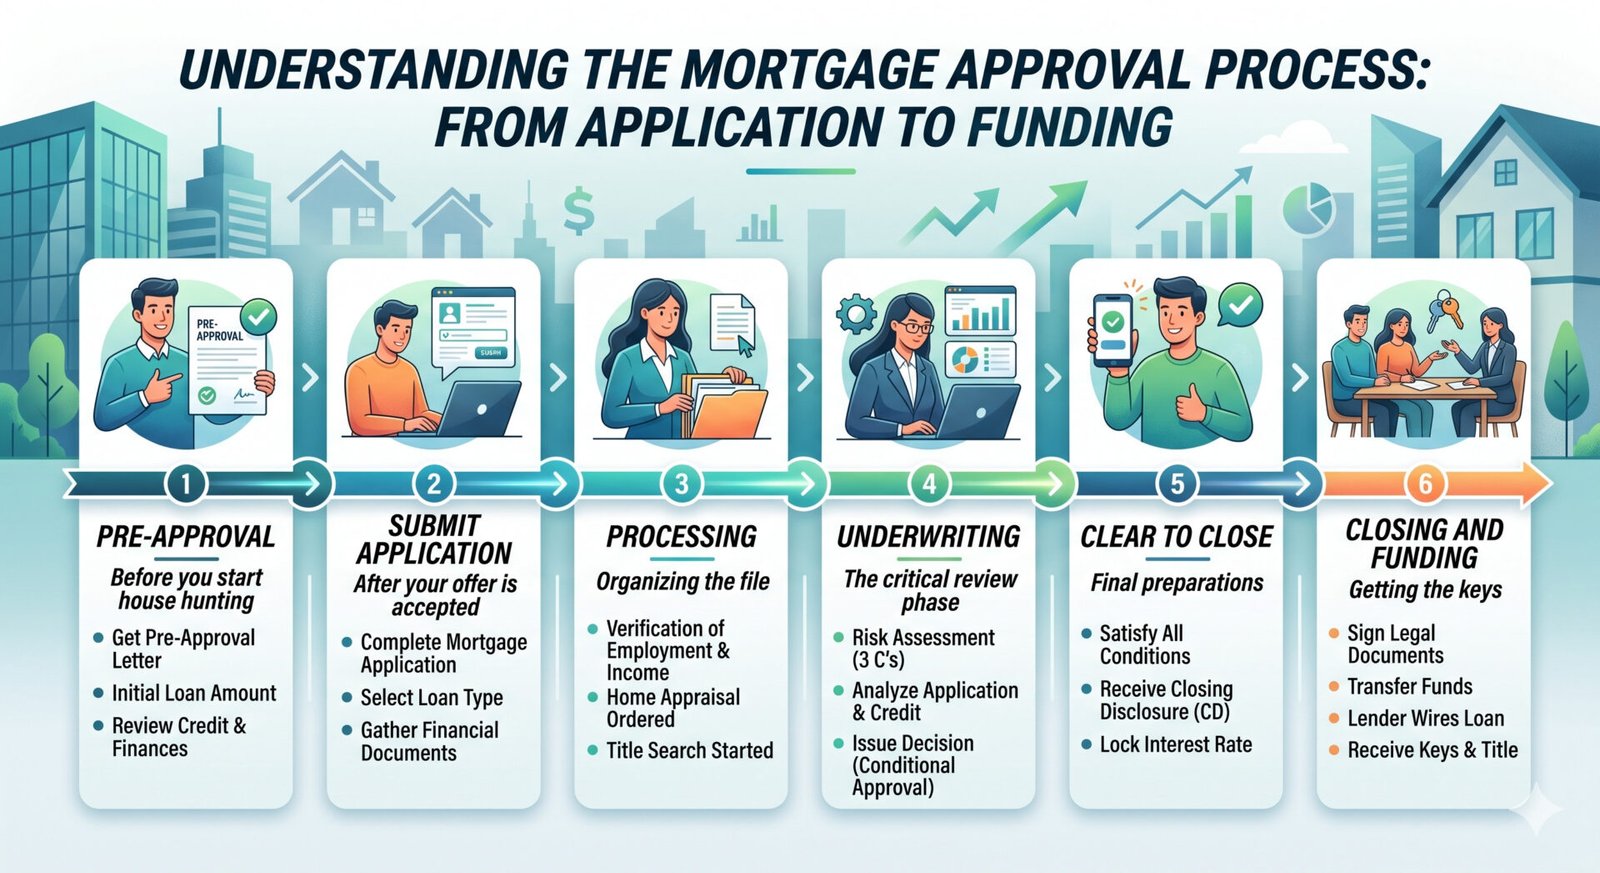
Understanding the Mortgage Approval Process: From Application to Funding
A Complete Guide for Ontario Home Buyers
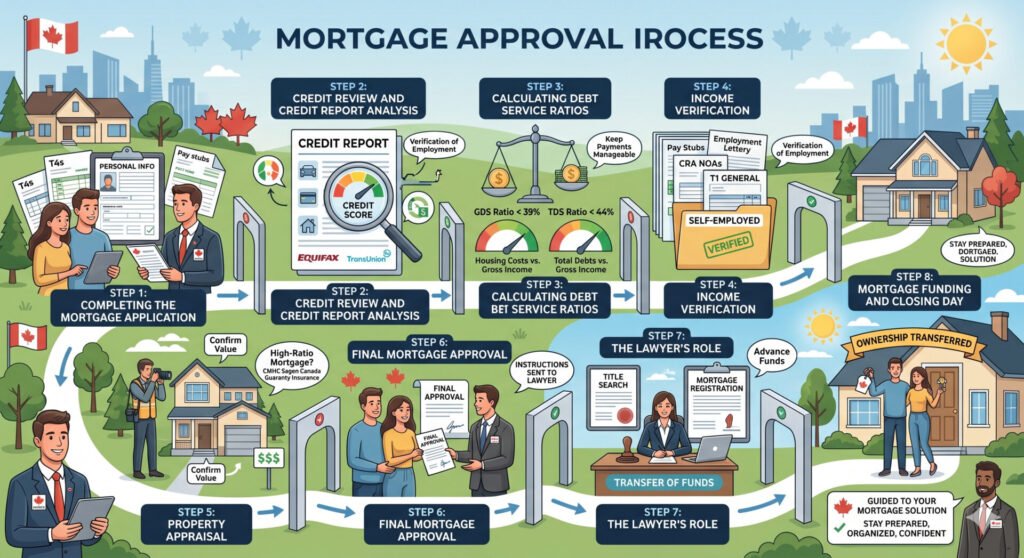
Buying a home is one of the biggest financial decisions most Canadians will ever make. Whether you’re purchasing your first home, refinancing an existing mortgage, or upgrading to a new property, understanding how the mortgage approval process works can make the experience much smoother and less stressful.
Many people believe getting a mortgage simply involves filling out an application and waiting for approval. In reality, lenders carefully review your finances, verify your income, assess your credit history, evaluate the property, and ensure you meet lending guidelines before advancing funds.
As a Mortgage Broker and Realtor with decades of experience helping Ontario families achieve homeownership, I’ve guided thousands of clients through this process. Here’s a step-by-step breakdown of what to expect.
Step 1: Completing the Mortgage Application
The mortgage approval process begins with a detailed application.
Your lender or mortgage broker will gather information about:
Personal Information
- Full legal name
- Date of birth
- Current address
- Marital status
- Employment history
Financial Information
- Employment income
- Other sources of income
- Existing debts
- Assets and savings
- Down payment source
Property Information
- Purchase price
- Property address
- Property type
- Intended use (owner-occupied or rental)
This information provides lenders with an overall picture of your financial situation and helps determine whether you qualify for financing.
Step 2: Credit Review and Credit Report Analysis
One of the most important steps in the approval process is reviewing your credit history.
Most lenders obtain a credit report from Equifax, TransUnion, or both. This report provides a detailed summary of your borrowing history and financial obligations.
Information Typically Found on a Credit Report
- Current and previous addresses
- Employment history
- Credit cards
- Car loans
- Lines of credit
- Student loans
- Existing mortgages
- Collections accounts
- Consumer proposals or bankruptcies
- Judgments and liens
- Credit inquiries
- Credit score and payment history
Why Credit Matters
Lenders use your credit report to:
- Verify debts disclosed on your application
- Review repayment history
- Calculate monthly obligations
- Assess financial responsibility
- Identify collections, bankruptcies, or judgments
- Determine overall lending risk
Consistently making payments on time and maintaining reasonable credit balances can significantly improve your chances of approval and help you secure better mortgage rates.
Step 3: Calculating Debt Service Ratios
Lenders use debt service ratios to determine how much mortgage financing you can comfortably afford.
Gross Debt Service Ratio (GDS)
The Gross Debt Service Ratio measures housing costs compared to your gross income.
Housing expenses include:
- Mortgage principal and interest
- Property taxes
- Heating costs
- Condo fees (if applicable)
Generally, GDS should not exceed 39% of gross annual income.
Total Debt Service Ratio (TDS)
The Total Debt Service Ratio includes housing costs plus other debts such as:
- Car loans
- Credit cards
- Lines of credit
- Personal loans
- Support payments
Typically, TDS should not exceed 44% of gross annual income.
These calculations help lenders determine the maximum mortgage amount you qualify for while ensuring your payments remain manageable.
Step 4: Income Verification
Lenders require documentation to verify income and confirm your ability to repay the mortgage.
For Salaried and Hourly Employees
You may be asked to provide:
- Recent pay stubs
- Employment letter
- T4 slips
- Canada Revenue Agency Notice of Assessment (NOA)
For Self-Employed Borrowers
Additional documentation is often required, including:
- Two years of Notices of Assessment
- T1 General tax returns
- Business financial statements
- GST/HST filings
- Business bank statements
Additional Documentation
Depending on your situation, lenders may also request:
- Bank statements
- Investment statements
- Proof of down payment
- Gift letters for gifted down payments
The objective is to verify that your income is stable, accurate, and sufficient to support mortgage payments.
Step 5: Property Appraisal
For many mortgage applications, the lender will require an appraisal.
An independent appraiser evaluates:
- Property condition
- Location
- Comparable sales
- Property size and features
- Current market conditions
The appraisal helps confirm the property’s value and protects both the lender and borrower.
What Happens if the Appraisal Comes in Low?
If the appraised value is lower than the purchase price, you may need to:
- Increase your down payment
- Renegotiate the purchase price
- Explore alternative financing options
High-Ratio Mortgages
When your down payment is less than 20%, mortgage insurance is typically required through insurers such as:
- CMHC
- Sagen
- Canada Guaranty
Although appraisals are often waived on insured mortgages, lenders or insurers may still request one if additional verification is needed.
Important: Appraisal fees are generally paid by the borrower and are not included in the mortgage amount.
Step 6: Final Mortgage Approval
Once all conditions have been satisfied, the lender issues final approval.
At this stage:
- Mortgage instructions are sent to your lawyer
- Interest rate and mortgage terms are confirmed
- Payment details are finalized
- Closing preparations begin
You will review and sign mortgage documents before the funding date.
Step 7: The Lawyer’s Role
A real estate lawyer or notary handles the legal aspects of your transaction.
Their responsibilities include:
- Conducting title searches
- Registering the mortgage
- Reviewing legal documents
- Coordinating the transfer of funds
- Paying outstanding taxes or liens if necessary
Typical Legal Costs
Legal fees often include:
- Legal service fees
- Title insurance
- Registration fees
- Disbursements
These costs are separate from your mortgage and should be included in your closing budget.
Step 8: Mortgage Funding and Closing Day
Funding is the final step of the mortgage process.
On closing day:
- The lender advances the mortgage funds
- Your lawyer transfers funds to the seller’s lawyer
- Ownership officially transfers to you
- The mortgage is registered on title
Once everything is complete, you receive the keys to your new home and begin making mortgage payments according to your agreed schedule.
Tips for a Smooth Mortgage Approval
To improve your chances of a successful approval:
Maintain good credit habits
Avoid taking on new debt before closing
Keep employment stable
Respond quickly to lender requests
Organize documents in advance
Save for closing costs in addition to your down payment
Working with an experienced mortgage professional can help identify potential issues early and keep your financing on track.
Final Thoughts
The mortgage approval process involves many steps, but understanding how each stage works can help you navigate the journey with confidence.
From the initial application and credit review to income verification, appraisals, legal documentation, and final funding, every step is designed to ensure both the borrower and lender are protected.
Being prepared, staying organized, and seeking professional guidance can make the process significantly easier and increase your chances of securing the right mortgage solution for your needs.
Need Mortgage Advice?
Whether you’re buying your first home, refinancing, renewing your mortgage, or investing in real estate, I can help.
Tony Slavin
Licensed Mortgage Broker & Realtor
Serving Oshawa, Durham Region, and all of Ontario
Contact me today for a no-obligation mortgage consultation and personalized financing advice.